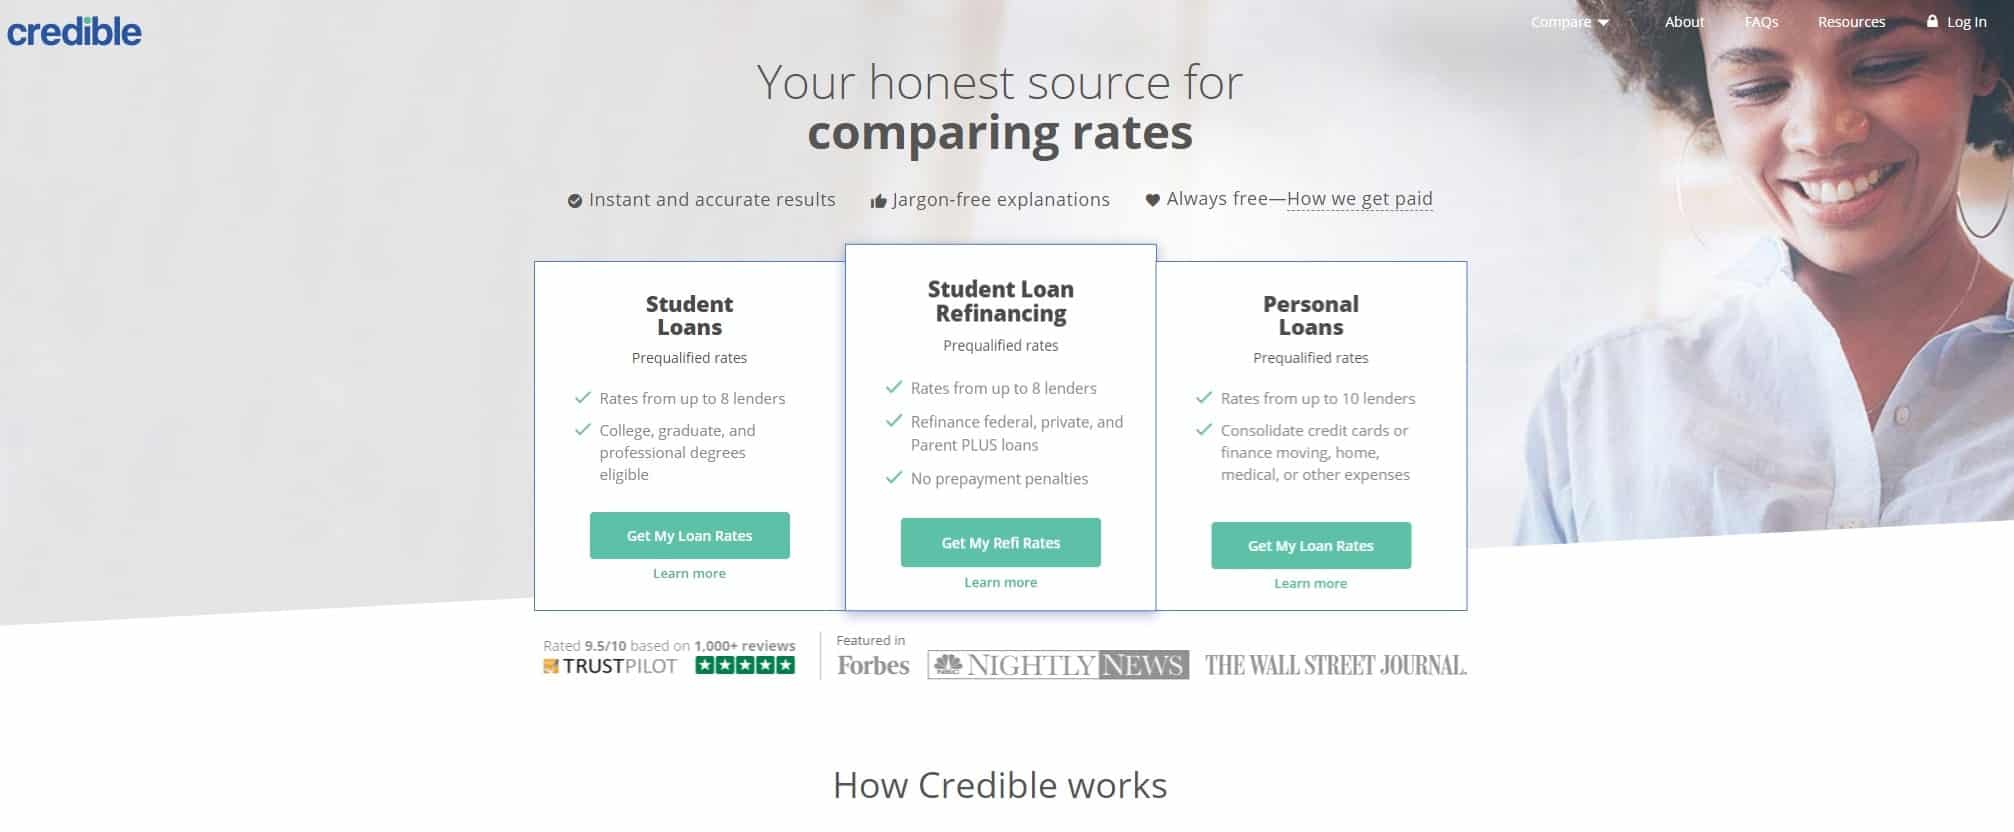
Credible doesn’t lend you anything. It’s a marketplace: you fill out one form, and it shows you prequalified refinance rates from the lenders on its platform side by side.
That saves you from typing the same income and loan details into five lender sites. It doesn’t show you every lender, though, and a prequalified rate isn’t a final offer. Here’s how it works and where it falls short.
The short answer
- Credible is a loan marketplace, not a lender. Your loan comes from whichever partner lender you pick.
- Getting prequalified rates is a soft credit check. The hard pull comes later, when you apply with one lender.
- None of Credible’s partner lenders charge origination fees or prepayment penalties. Terms run 5 to 20 years, depending on the lender.
- It covers a good chunk of the refinance market, but not all of it, so a second quote elsewhere is worth the two minutes.
How Credible student loan refinancing works
- Fill out one form. You give your school and degree, income, and how much you want to refinance, and you create a Credible account.
- See prequalified rates. Credible runs a soft credit check, so your score isn’t affected, and shows offers from its partner lenders with different terms and fixed or variable rates.
- Pick a lender and apply there. This is where the lender does a hard credit pull and checks your documents. The final rate can differ from the prequalified one.
- The new lender pays off your old loans. From then on you make one payment to the new loan.
Prequalified rates aren’t an offer of credit.
So how close are they? Think of them as a good estimate that firms up once a lender sees your full application and pulls your credit for real.
Which lenders you’ll see
The lineup changes, but when we checked Credible’s refinance table it listed ten lenders: MEFA, Brazos, SoFi, RISLA, EdvestinU, Earnest, LendKey, ELFI, INvestEd and Citizens.
That’s a good spread, including a few smaller names you probably wouldn’t find on your own. What’s missing matters too. Splash Financial and KeyBank weren’t in that table, so checking one of them as well covers lenders Credible can’t show you.
Where Credible helps, and the catch
The big win is time. One form, one soft check, and you can see within minutes whether refinancing is even worth chasing. If every prequalified rate is higher than what you pay now, you’ve got your answer and your credit report hasn’t been touched.
A marketplace only shows its own partners, and the rate you see isn’t locked until a lender approves you. The lender’s full review decides the final number. And once you apply, expect a hard pull from that lender.
Run any offer you get through our student loan refinance calculator before you accept it. A lower rate on a longer term can still cost you more in total interest.
Before you refinance federal loans
Federal student loans can’t be refinanced inside the federal system. Refinancing them with a private lender takes them out for good, and Federal Student Aid says plainly that you lose the benefits.
That means no income-driven repayment (RAP or IBR), no Public Service Loan Forgiveness or other federal forgiveness, no federal deferment or forbearance, and no federal death or disability discharge. There’s no way back once the new loan pays off the old ones.
Credible also covers private student loans for school, personal loans and mortgages. For student loans, the useful part is refinancing private loans, or federal loans you’ve already decided to give up the federal options on. Our guide to whether you should refinance helps with that call.
Bottom line: Credible is a handy first stop for comparing private refinance offers without a hit to your credit. Try Credible for one round of prequalified rates, then get one more quote from a lender it doesn’t carry.
*Requesting prequalified rates on Credible is free and doesn’t affect your credit score. However, applying for or closing a loan will involve a hard credit pull that impacts your credit score and closing a loan will result in costs to you.
Get a second quote from lenders outside Credible
- See offers from Splash’s lending partners with a soft credit pull. Continuing to apply leads to a hard pull.
- No application fees, no origination fees and no prepayment penalties.
- Fixed terms of 5 to 20 years and variable terms of 5 to 25 years. Minimum $5,000.
- Best fit: private loans, a four-year degree, and credit of 700 or higher.
Splash Financial is a marketplace, not the lender. Your loan comes from one of its lending partners, and some are credit unions you’d need to join. Not all rates and amounts are available in every state. If you refinance federal loans through Splash, you lose federal benefits for good.
No. Credible is a marketplace that shows prequalified rates from partner lenders. Your loan is made by the lender you choose.
No. Credible uses a soft credit check for prequalified rates. Applying with a lender afterward involves a hard credit pull.
Requesting prequalified rates on Credible is free, and none of its partner lenders charge origination fees or prepayment penalties.
The list changes. Its refinance table has included MEFA, Brazos, SoFi, RISLA, EdvestinU, Earnest, LendKey, ELFI, INvestEd and Citizens. Splash Financial and KeyBank were not on it.
Only if you have decided to give up federal benefits for good. Refinancing federal loans with any private lender ends access to income-driven repayment, federal forgiveness including PSLF, and federal deferment and forbearance.
Sources (4)
We use primary sources wherever we can: Federal Student Aid, the U.S. Department of Education, the IRS, federal regulations and each company’s own site.
- Credible. Refinance student loans. credible.com. Accessed October 22, 2026.
- Federal Student Aid. Financial aid dictionary: refinance. studentaid.gov. Accessed October 22, 2026.
- Splash Financial. Student loan refinancing. splashfinancial.com. Accessed October 22, 2026.
- KeyBank. Student loan refinancing. key.com. Accessed October 22, 2026.


